Roof Insurance Claim Assistance in Scottsdale, AZ
Home / Commercial Roofing Services / Roof Insurance Claim Assistance
Roof insurance claim assistance in Scottsdale provides an inspection record and repair estimate while claim decisions stay with the policyholder.
Roof insurance claim assistance means giving the property owner a clear record of observed roofing conditions and a repair scope tied to the assigned building. It does not mean deciding whether a policy covers a loss or promising that an insurer will pay. For a Scottsdale commercial roof claim, we identify the reported event, inspect accessible roof areas, document what we can verify and prepare an estimate for the roofing work the findings support.
For a building near Scottsdale Airport or in Scottsdale Airpark, the street address, roof plan and claim contact tie the inspection to the right property. Old Town Scottsdale is a commercial submarket, but neither district identity nor a regional event establishes impact at the assigned roof. We record building-specific observations and keep unsupported cause, coverage or quantity statements out of the roofing scope.
The roofing record answers a physical question
Before scheduling, we ask what the owner needs the roof contractor to document: an active leak, reported wind or hail impact, a fallen object, visible damage or a repair estimate after another inspection. We review the claim or work reference the owner chooses to provide, along with previous roof plans, repairs and condition reports. The policyholder or authorized representative directs access and confirms which roof areas are part of the requested review.
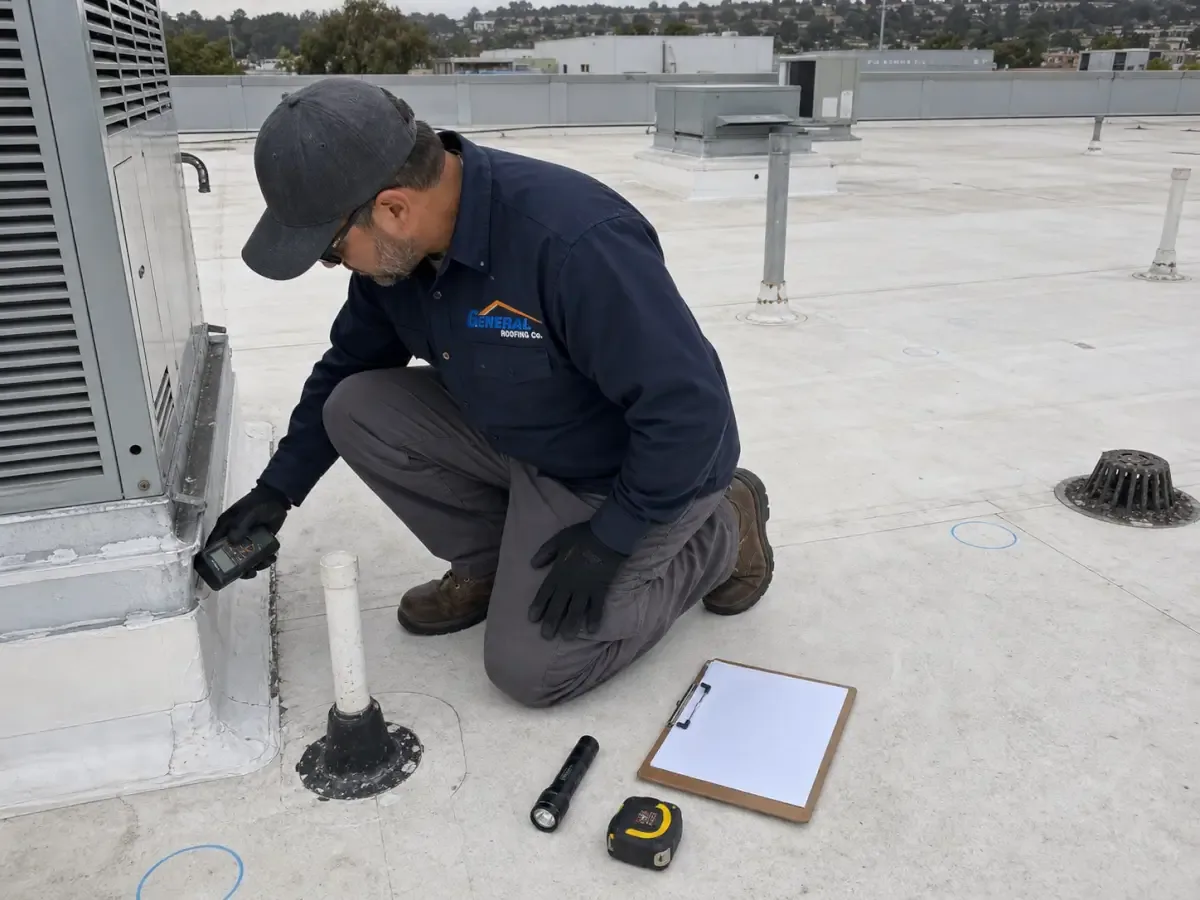
Our visit records observed conditions, locations, measurements where taken, photographs, access limits and the work recommended for the roof system. If a condition cannot be confirmed without opening the roof, we identify that next step and request the owner’s authorization. A roofing report is evidence about the physical roof at the time of inspection; it is not an adjuster’s coverage decision, policy interpretation or legal opinion.
Commercial policy terms determine the notice, coverage and documentation requirements for a claim. The owner should refer policy questions and deadlines to the insurer or qualified representative handling the file.
The inspection separates observation from attribution
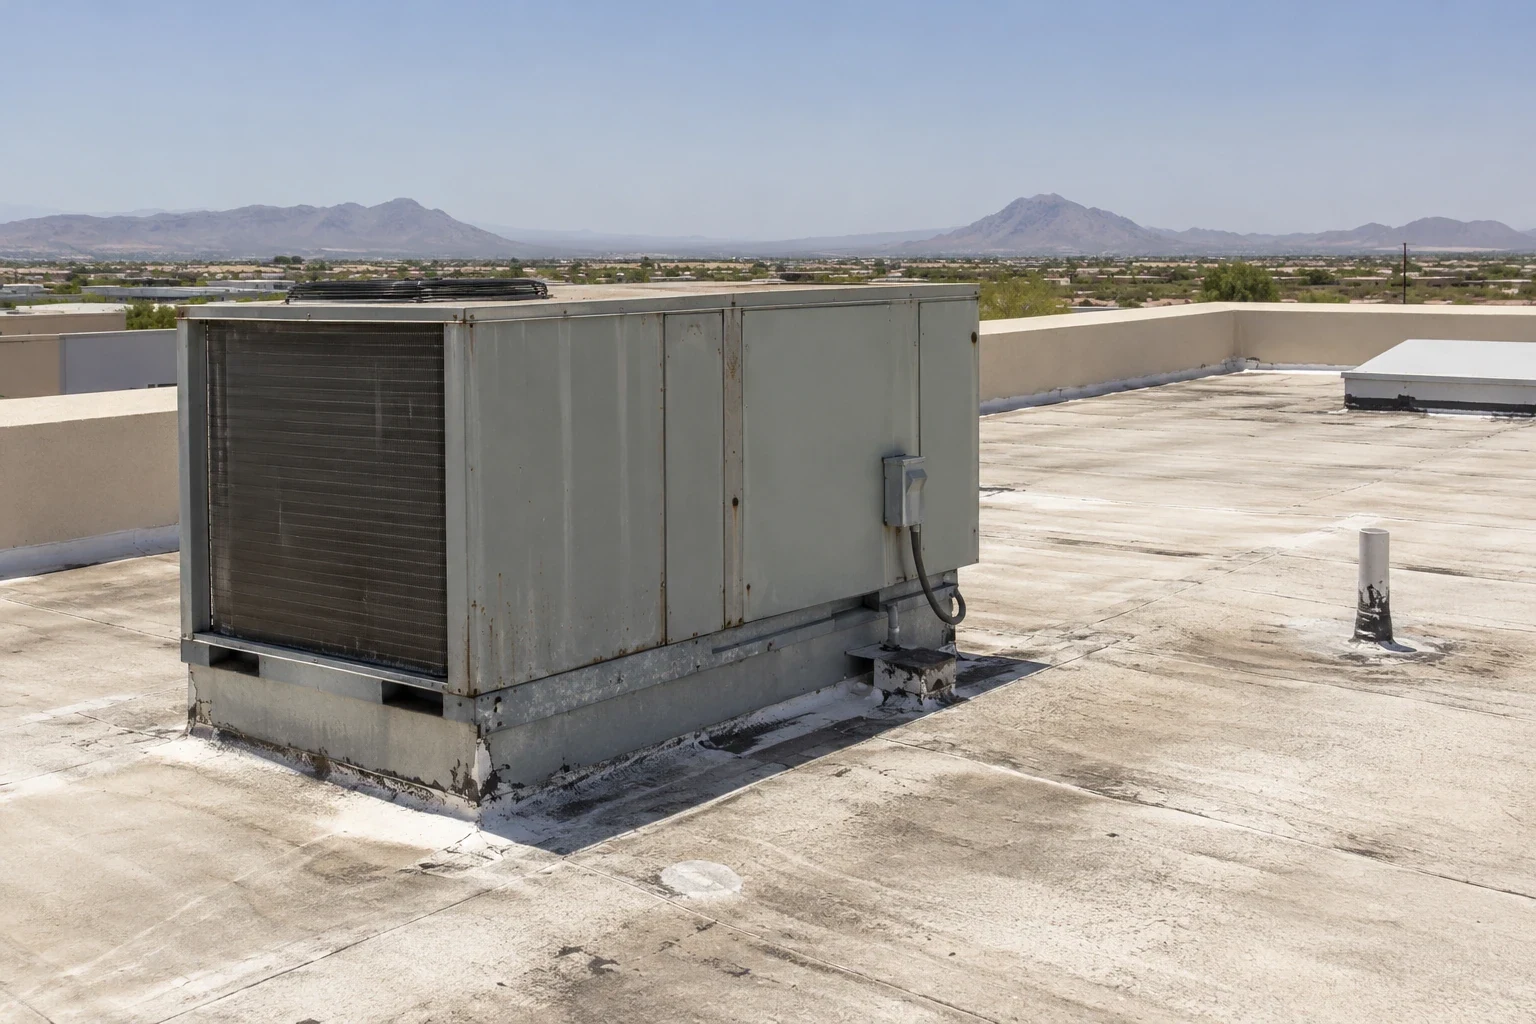
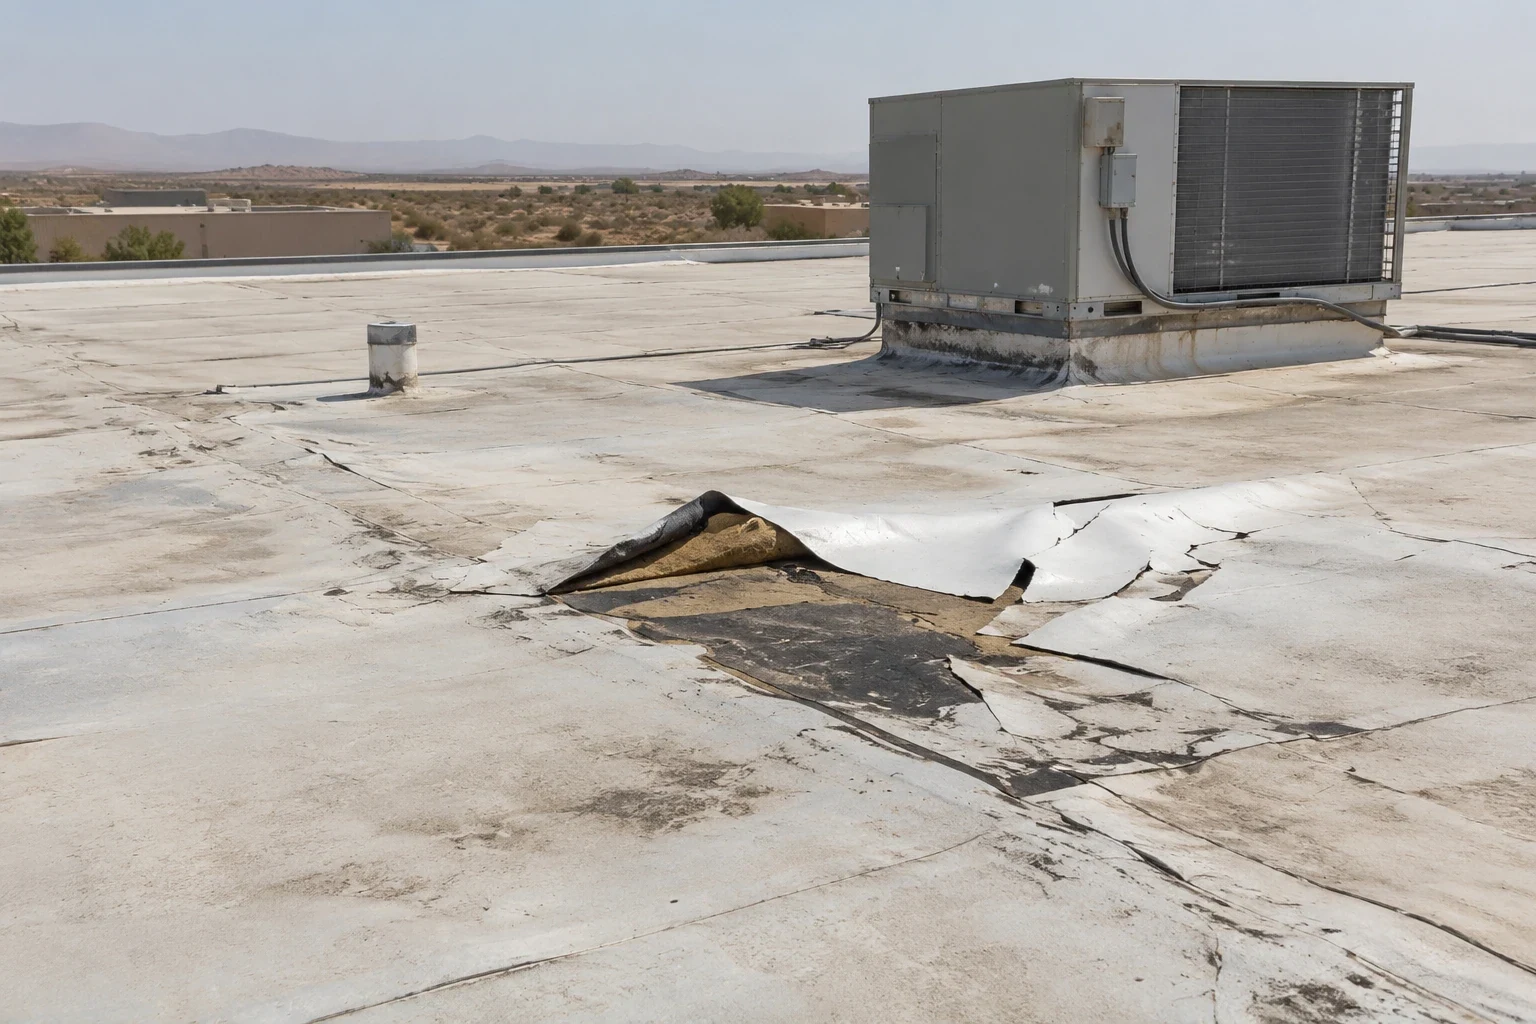
We compare accessible roof conditions with the reported date and type of event, prior repair records and available before-event photographs. The inspection may review membrane, surfacing, seams, perimeter metal, flashings, drains, curbs, skylights, interior leak reports and visible impact locations. Each observation is tied to a roof area and described as visible damage, an existing condition, a symptom needing investigation or an area that could not be accessed.
A leak that appears after an event does not by itself show where water entered or whether the condition is new. If the available record cannot distinguish recent damage from earlier wear or repair, we state that limit. A broader commercial roof inspection may help document areas beyond the reported symptom. If a storm impact was recently reported, storm damage roof repair addresses urgent protection and repair planning, while preserving the need for claim-specific direction from the owner.
Where the owner’s appointed adjuster or consultant wants to view the roof, we can coordinate a site meeting with the property contact. The owner sets that invitation and any shared documents. We describe roofing observations and answer questions about the proposed repair without claiming authority over another party’s assessment.
The estimate follows the verified repair detail
A roofing estimate identifies the observed area, installed material where known, repair operation, preparation, replacement layers if needed, flashing or seam transitions, access assumptions and exclusions. Measurements and quantities correspond to the documented area. If the repair amount could change after an approved opening, we state the condition that would require a revised scope and how the owner will review that change.
If concealed moisture or damaged board is found, we identify the opening location, additional material and completed tie-in needed to restore the assembly. Insulation and cover-board work is included only where confirmed and approved. A line item for commercial roof repair should describe the actual membrane and connection rather than imply that every surface symptom needs full replacement.
The estimate can be revised when new site evidence changes the work. We identify the additional observation, photographs and quantity behind a revision, then provide it to the property contact for authorization. The policyholder or representative decides whether and how to submit that material to the insurer. Our price for roofing labor and material is not a statement that an insurance payment will match it.
The owner controls claim communication
We can provide a dated inspection report, labeled photographs, an estimate and a repair completion record to the owner or to a person the owner has authorized to receive them. If an insurer requests additional roof information, the owner can confirm the request and identify what may be shared. Claim notices, policy interpretation, negotiation, settlement decisions and insurer deadlines remain with the policyholder and the parties authorized to handle the claim.
When immediate temporary protection is considered, the owner should follow building safety procedures and check the commercial policy or insurer’s instructions about documentation and emergency work. We record the temporary measure, the area it protects and any follow-up that remains. Emergency work is kept distinct from permanent repair, and necessary safety action is not represented as proof of coverage.
A claim estimate and a roof repair authorization are separate decisions. Before permanent work begins, the property representative approves the scope, access, work period and any change-order process. If another trade must move equipment or restore a service line, we identify that responsibility so the roofing work does not assume a task outside the approved contract.
Closeout records show what was completed
After approved roofing work, we record the repaired area, material installed, completed details, photographs, replaced layers and any deferred condition. If the scope changed after an opening, the record connects the revised quantity with the observed condition and owner approval. A closeout report describes the work performed; it does not amend the insurance policy or certify an insurer’s payment decision. If the roof record depends on another trade’s findings, identify that dependency before pricing.
For a multi-building portfolio, each estimate and report should retain its own address, roof section, event reference and unresolved items. A roof condition report can keep this repair distinct from unrelated findings at another property. Property managers can then track the approval, roofing work and remaining questions through their normal records.
When the insurer or policyholder requests additional documentation, the owner can send the appropriate report, images and invoice. We can clarify the roofing operation shown in that record if authorized, while keeping policy questions with the designated insurance contact.
Commercial Roofing Questions
Does a roofing estimate mean insurance will pay?
No. It describes roofing work and its price based on the observed conditions. Coverage and payment depend on the policy and insurer’s review.
Can you tell whether my commercial policy covers roof damage?
No. We document roofing conditions and proposed work. The policyholder should ask the commercial insurer or its authorized representative about coverage and requirements.
What should I provide before a roof claim inspection?
The building address, claim or work reference if available, event date, reported symptoms, roof records, prior repairs, access contact and the areas the owner wants reviewed.
Can the estimate change after work begins?
It can change if an approved opening reveals conditions that affect the repair. We document the finding, added work and amount and request owner direction before proceeding.
Can you meet the insurance adjuster on site?
With the owner’s authorization, we can coordinate access and describe the observed roof conditions and repair detail. The owner or authorized representative manages the claim discussion.
Request a Roofing Claim Inspection
Provide the property address, claim or work reference, reported event, current roof symptoms and an authorized access contact. We can document the roofing conditions and prepare a repair estimate for the owner’s review.
Call or Email
Helpful to have ready:
The property address and a building contact
Where water or damage shows up inside
The roof type and age, if you know them
Photos and any past roof reports